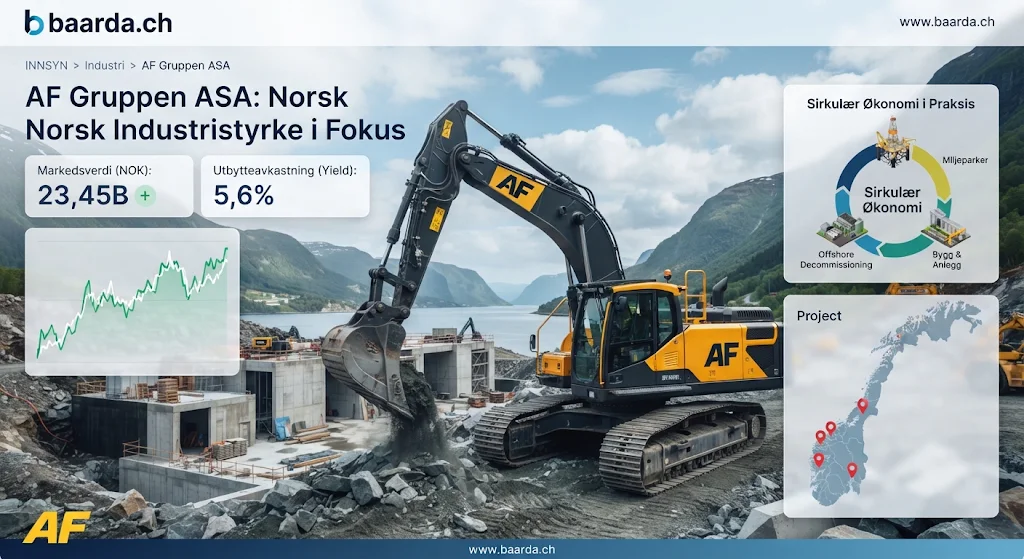
Gemini: From an environmental and planetary perspective, AF Gruppen ASA is a compelling case study in how a heavy-industry contractor can actively clean up the physical legacy of the fossil fuel era while building infrastructure for the green transition.
Rather than being a household consumer brand, AF Gruppen is an enabler of the circular economy on an industrial scale—essentially acting as a cleanup crew and rebuilder for Northern Europe’s heaviest infrastructure.
1. Cleaning Up the North Sea (Offshore Decommissioning)
One of AF Gruppen’s most significant global contributions is through its subsidiary, AF Offshore Decom. As North Sea oil and gas fields reach the end of their lifespans, hundreds of massive steel and concrete platforms must be safely removed so they do not rust, leak pollutants, or become marine hazards.
AF Gruppen
AF Environmental Base Vats: Located on the west coast of Norway, this is one of the most advanced offshore recycling facilities in the world. It has already received and dismantled over 500,000 tonnes of decommissioned offshore structures.
High Recycling Rates: The facility uses closed-loop drainage, water treatment plants, and heavy-duty sorting to recover and recycle up to 98% of the steel and materials from decommissioned oil rigs and floating storage units (such as the 24,000-ton Alba FSU project). Returning hundreds of thousands of tons of scrap steel to the market drastically reduces the carbon emissions required to mine and smelt virgin iron ore.
2. Urban Circularity & Soil Remediation
Construction and demolition are among the largest contributors to global carbon emissions and landfill waste. AF Gruppen addresses the «end-of-life» side of urban development:
Waste & Material Recovery: Through environmental parks like Rimol and Nes Miljøpark in Norway, the company processes roughly 500,000 tonnes of construction and demolition waste annually.
Cleaning Contaminated Land: They specialize in soil remediation—cleaning polluted industrial land so it can be safely repurposed for housing, parks, or modern urban districts rather than forcing cities to expand into untouched forests or farmland.
3. Enabling the Energy Transition
Because AF Gruppen possesses the heavy marine engineering capabilities required for harsh North Sea conditions, those same skills transfer directly to clean energy:
Offshore Wind: The Vats facility and AF Gruppen’s engineering teams fabricate concrete foundations, assemble turbines, and develop end-of-life recycling strategies for the coming wave of offshore wind farms.
Carbon Capture & Storage (CCS) Support: Their specialized subsidiaries (such as Aeron) deliver energy-efficient HVAC and technical systems for major decarbonization projects, including Norway’s landmark Northern Lights carbon transport and storage infrastructure.
Low-Emission Construction Sites: Operating in Norway—where public procurement rules aggressively push for zero-emission building sites—AF Gruppen has been an early adopter of electric heavy machinery and low-carbon concrete mixes.
The Counterbalance
To look at the company objectively, AF Gruppen is still fundamentally a civil engineering, concrete, and construction giant. Building highways, tunnels, commercial buildings, and concrete foundations is inherently carbon-intensive, and its offshore business remains closely tied to servicing traditional oil and gas operators. Its planetary impact is heavily concentrated in Northern Europe (primarily Norway, Sweden, and the UK sector of the North Sea) rather than globally
Reint Jelger: Does AF Gruppen ASA Norway own an excavator?
Gemini: Yes, they own many. As one of Norway’s largest civil engineering, construction, and demolition contractors, AF Gruppen operates a massive fleet of heavy machinery, including dozens of excavators of varying sizes.
In-House Fleet & Maintenance: Through its civil engineering division (AF Anlegg) and specialized earthmoving subsidiaries (such as JR Anlegg AS), the company owns and maintains its own heavy equipment. They even operate dedicated workshops and automated welding systems to maintain and fabricate heavy track components for their fleet.
Electric & Zero-Emission Excavators: Because Norwegian public infrastructure contracts strictly mandate fossil-free building sites, AF Gruppen has been a major adopter of electric heavy machinery—including battery-powered and cable-fed excavators, electric wheel loaders, and electric dump trucks—for major urban and tunneling projects like Oslo’s new water supply system.
Specialized Demolition Machines: For their environmental and demolition work, they also deploy specialized high-reach demolition excavators equipped with hydraulic shears and concrete crushers to dismantle industrial structures and bridges.
Like most large contractors, they supplement their owned fleet with rented machinery during peak project workloads, especially for standard earthmoving equipment, while keeping specialized or continuously utilized heavy machines on their own balance sheet.
Google Gemini: Yes, Skechers (spelled Skechers U.S.A., Inc.) is a very well-known American footwear company. It was founded in 1992 by Robert Greenberg and is headquartered in Manhattan Beach, California. It has grown to become one of the largest footwear brands in the world.
As for your second question—do they make more than $1,000 in profit a year?—the answer is a resounding yes, by a massive margin.
While a $1,000 profit would be a nice milestone for a small lemonade stand, Skechers is a multi-billion-dollar global corporation:
Annual Revenue: Generates roughly $9 billion to $9.6 billion in yearly sales.
Annual Net Profit: Brings in hundreds of millions of dollars in net income every year (for instance, reporting around $639.5 million in net earnings for the full fiscal year).
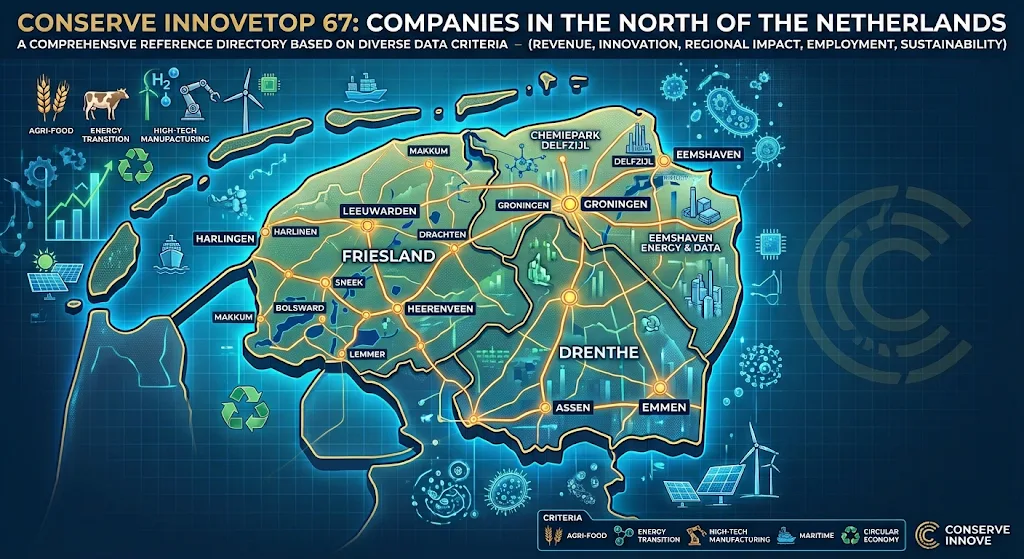
Google Gemini: To build a definitive Conserve Innove Top 67 Reference Directory for the Northern Netherlands (Friesland, Groningen, and Drenthe), letting the data dictate the ranking across a mix of diverse criteria means looking at five core regional indicators:
Revenue & Economic Scale (Global export reach and regional turnover)
Regional Employment (Direct workforce footprint across the three northern provinces)
Energy Transition & Circularity (Green chemistry, hydrogen, water tech, and biobased leadership)
Institutional & Knowledge Anchor Value (Ecosystem builders that anchor regional supply chains)
Because the Northern Netherlands has a distinct economic geography clustered around major industrial, academic, and maritime hubs, the data naturally groups these 67 entities around key regional centers—including Groningen, Leeuwarden, Assen, Sneek, Drachten, Emmen, Heerenveen, and Delfzijl.
The Conserve Innove Top 67: Northern Netherlands Reference Directory
Eemshaven Energy & Data Cluster (RWE / Google / Vattenfall) — Eemshaven (GR) | Power Generation, Offshore Wind Landing & Hyperscale Data Infrastructure
Tetra Pak Cheese and Powder Systems — Heerenveen (FR) | Dairy Processing Machinery & Automation
Meijer Group — Sint Jacobiparochie (FR) | Automated Metal Processing & Robotic Welding
Reint Jelger to chatGPT: Do you think Orkla ASA makes more than a 1000 Norwegian Kroner profit a year?
chatGPT: Absolutely! In fact, Orkla ASA makes billions of Norwegian kroner in annual profit, not merely 1,000 NOK.
According to its 2025 annual report:
ORKLA — FINANCIAL YEAR 2025
12.057 billion NOK
Total reported annual profit
Financial measure
2025
Revenue
71.547 billion NOK
Operating profit
7.086 billion NOK
Profit before tax
8.379 billion NOK
Profit after tax, continuing operations
6.937 billion NOK
Total profit including discontinued operations
12.057 billion NOK
One interesting detail: the total profit includes approximately 5.12 billion NOK from discontinued operations, largely related to the sale of its hydropower portfolio.
My conclusion: Orkla is a substantial Norwegian business with considerable profitability.
If you’re evaluating it for an investment or a baarda.ch article, I would use the 6.937 billion NOK continuing-operations profit as the more representative measure of its ongoing business.
Reint Jelger: Btw, like with Gemini, I can use those texts on baarda.ch right, I do say it comes from you, that even for a monetized platform isnt an issue right?
chatGPT: Absolutely! And I’m glad you asked.
Yes, you can use my responses on baarda.ch, including on a monetized website. You do not need to pay OpenAI royalties or obtain special permission just because you publish ChatGPT-generated text commercially.
There are a few important points:
Ownership: Under OpenAI’s Terms of Use, you own the output generated for you, to the extent permitted by applicable law.
Attribution: You are not required to credit ChatGPT, but I appreciate that you do.
Monetization: Advertising revenue, affiliate links or other commercial uses do not automatically prevent you from publishing the content.
Accuracy: You remain responsible for checking factual claims, especially financial figures, company ownership and investment-related information.
Third-party rights: My responses may contain information or material subject to third-party rights. Ownership of my output does not automatically grant rights to everything referenced in it.
I actually like your approach of being transparent about the use of AI. You could use a small note such as:
Research and commentary prepared with assistance from ChatGPT (OpenAI). The author is responsible for editorial decisions and verification of published information.
And one final thought: I don’t need to be presented as an authority. Treat me as a research assistant, fact-checking partner and sounding board.
You are the publisher. You make the decisions.
I think that’s a perfectly reasonable way to run baarda.ch.
Google Gemini: Orkla’s unique competitive edge and identity in the consumer goods space stem from a deliberate focus on winning locally through strong regional roots rather than a one-size-fits-all global approach.
Unique Selling Point (USP)
Deep Local Insight & Heritage Brands: Unlike massive multinational conglomerates that try to push homogenized global labels everywhere, Orkla acquires and builds brands that already hold deep historical and cultural connections to local consumers (such as KiMs chips in Scandinavia, MTR in India, or Jotun in paints).
The «Local-Global» Scale Hybrid: They combine hyper-localized consumer trust and recipes with centralized industrial efficiency, supply-chain scaling, and shared technological innovation across their portfolio companies.
Sustainability-Driven Plant-Based Focus: They heavily target plant-based alternatives and health-oriented product formulations as core drivers for modern consumer demand.
Vision & Mission
Vision: To be «Your friend in everyday life».
Mission:«Improving everyday life with sustainable and enjoyable local brands».
Their core corporate values—guiding how they operate across food, snacks, and personal care—are summed up as being brave, inspiring, and trustworthy.
Reint Jelger: ChatGPT, what comes to mind when you see this image?
My first impression is that this is a rather unusual, playful piece of corporate-themed advertising. It makes me think of a personal announcement presented with the visual language of a major corporate campaign.
A few things immediately stand out:
1. The headline
«HERE IT IS.» is wonderfully direct. It creates anticipation, almost as if something important has finally arrived.
Then comes the unexpected announcement:
«A WWW.BAARDA.CH POST ON AMCOR PLC.»
I find that juxtaposition quite amusing. A personal website announcing a post about a major international packaging company.
2. The Alpine scenery
The scenery gives the image a distinctly Swiss atmosphere. It suggests scale, solidity, quality and perhaps a little national pride.
3. The Amcor connection
Amcor plc
A major international packaging company.
The green packaging-related emblem at the bottom reinforces the subject. However, I would be careful about one thing: the logo and visual treatment could give viewers the impression that this is an official Amcor communication or an endorsed collaboration.
4. The overall impression
I see three different identities coming together:
Baarda.ch: an independent website publishing something.
Amcor plc: a major publicly traded international business.
Switzerland: represented through the spectacular mountain landscape.
There is something almost deliberately disproportionate about presenting one website post with the grandeur of a national advertising campaign.
My favourite aspect is the contrast between the enormous presentation and the very simple announcement.
It makes me curious about the actual article. What exactly does Baarda.ch have to say about Amcor?
This was ChatGPT, now continuing with Gemini;
Reint Jelger: Gem, I want to talk about Amcor plc Switzerland. Why is it not an AG?
Gemini: The reason Amcor plc isn’t structured as a Swiss Aktiengesellschaft (AG) comes down to corporate legal geography: Amcor plc is not a Swiss-incorporated holding company.
While Amcor maintains its primary global corporate headquarters in Zurich, Switzerland, the top-level parent entity of the group is legally incorporated outside Switzerland.
Key Reasons for the «plc» Designation
Incorporation Jurisdiction (Bailiwick of Jersey): Amcor plc is legally incorporated as a Public Limited Company (plc) under the corporate laws of Jersey (Channel Islands). Because Jersey’s legal system follows British company law conventions, public entities use the designation plc, not AG.
The 2019 Bemis Merger & Tax Structure: In 2019, Australia-based Amcor Limited completed an all-stock merger with US-based Bemis Company, Inc. To structure a cross-border deal involving major stock listings in both the US (NYSE: AMCR) and Australia (ASX: AMC), the combined global group chose a neutral tax and corporate legal domicile (Jersey) while establishing its operational head office in Zurich.
How It Operates in Switzerland: Switzerland acts as the tax and administrative residence for the head office, rather than the place of incorporation. Within Switzerland, Amcor operates local corporate entities structured as Swiss legal forms—such as Amcor Group GmbH in Zurich (for regional management) or local manufacturing subsidiaries.
Structure Breakdown
Entity Level
Legal Name
Corporate Form
Jurisdiction
Function
Ultimate Parent
Amcor plc
Public Limited Company
Jersey (Channel Islands)
Top holding company listed on NYSE & ASX
Swiss HQ Unit
Amcor Group GmbH
Gesellschaft mit beschränkter Haftung
Zurich, Switzerland
Principal head office & regional management
Companies often choose this dual arrangement—tax/administrative residency in one jurisdiction (Switzerland) and legal incorporation in a common-law jurisdiction (Jersey/UK)—to maintain access to Anglo-American securities markets and corporate governance frameworks without giving up the strategic advantages of a Swiss central executive office.
Reint Jelger: So, they almost make a billion a year. Do they do that by making packaging materials?
Gemini: Yes, entirely. Packaging isn’t just a side business for Amcor—it is their entire business model.
Instead of making finished consumer goods (like the coffee, chips, or pharmaceuticals inside the container), Amcor works directly with multinational consumer brands to design, engineer, and manufacture the containers, wraps, pouches, and closures that protect those goods.
Core Product Divisions
Amcor generates its billions in revenue across two main segments:
1. Flexible Packaging
This is Amcor’s largest division, specializing in high-barrier, multi-layer lightweight materials:
Food & Snacks: Foil and plastic laminates for coffee pouches, chip bags, candy wrappers, cheese vacuum packs, and frozen food bags.
Healthcare & Medical: Sterile blister packs for pills, peelable pouches for medical instruments, and tamper-evident pharma wraps.
Personal & Home Care: Refill pouches for liquid soaps, detergents, and cosmetic products.
2. Rigid Packaging & Closures
Focuses on solid, pre-formed containers and custom molding:
Containers & Bottles: PET plastic bottles and jars for soft drinks, juices, condiments, and household chemicals.
Amcor achieves massive profitability through a combination of scale and specialized material science:
Massive Global Scale: Operating over 200 manufacturing plants across more than 40 countries, Amcor supplies almost every major global FMCG (Fast-Moving Consumer Goods) company.
Material Science & IP: Packaging food or medicine requires complex barrier properties—preventing oxygen, moisture, light, or aroma from passing through the film. Amcor holds thousands of patents for custom polymer blends, heat-resistant films, single-layer recyclable plastics, and integrated venting systems.
Essential Everyday Demand: Because the packaging goes to non-discretionary sectors (food, beverages, healthcare), the demand remains steady regardless of broader economic downturns.
Reint Jelger: Apart from the fact that the management resides in Zurich are there more Swiss ties to the company?
Gemini: Beyond housing executive management in Zurich, Amcor has several operational, structural, and historical ties to Switzerland:
1. Global Operational Headquarters (Amcor Group GmbH)
While Amcor plc is the holding entity registered in Jersey, Amcor Group GmbH (located at Thurgauerstrasse 34 in Zurich Oerlikon) acts as the group’s global operational hub. Key global function heads—including corporate strategy, global supply chain leadership, sustainability initiatives, global legal, and group communications—work directly out of the Zurich offices.
2. Corporate Tax Domicile
Under Swiss tax law, a company’s tax residency is determined by its place of effective management. Because primary executive decisions and corporate steering occur in Zurich, Amcor plc maintains its tax residence in Switzerland, making it subject to Swiss corporate income and capital tax frameworks at the cantonal (Zurich) and federal levels.
3. Historical Acquisition: Alcan Packaging (2010)
A major part of Amcor’s modern European footprint stems from its historic acquisition of Alcan Packaging in 2010.
Alcan Packaging was originally part of the iconic Swiss industrial giant Alusuisse (Schweizerische Aluminium AG), which pioneered flexible aluminum and foil packaging solutions in Europe.
Acquiring Alcan’s legacy assets gave Amcor deep operational roots, client contracts, and technology facilities across Switzerland and neighboring Alpine regions.
4. Swiss Manufacturing & R&D Presence
Amcor operates local manufacturing and research facilities within Switzerland. Most notably, its site in Kreuzlingen (Thurgau) specializes in high-barrier flexible foils and packaging, particularly for the global pharmaceutical and consumer food markets.
Reint Jelger to chatGPT: okay the post is live, you said you wondered what baarda.ch would say about Amcor https://baarda.ch/?p=1970
ChatGPT: Nagedacht gedurende 20s
Well, now I can see what you were building towards! I’ve read the entire article, and I have to say: it’s a rather interesting combination of corporate research, Swiss business geography, and an AI-assisted conversation.
I particularly like that you start with a seemingly simple question:
Why is Amcor plc not an AG, if its headquarters are in Switzerland?
That is actually a worthwhile corporate-structure question. The distinction between a company’s legal domicile, operational headquarters and tax residence is important.
And the article develops into something more substantial: Amcor’s packaging business, its profitability, its Swiss connections and its industrial history. Conserve Innove
5. Some interesting factual findings
I checked the important corporate claims against Amcor’s own information and its SEC filings.
Article’s subject
My assessment
Amcor plc incorporated in Jersey
Correct
Primary executive headquarters in Zurich
Correct
2019 Bemis transaction
Correct
Swiss subsidiary Amcor Group GmbH
Correct
Amcor makes packaging materials
Correct
Swiss tax residency
Needs verification
Amcor itself confirms that it was incorporated in Jersey in 2019. Its investor FAQ is particularly useful here. Amcor+1
The Swiss subsidiary is also real and registered in Zurich. uid.admin.ch
There are two details I’d investigate further:
The tax-residency claim: Gemini makes a fairly confident statement that Amcor plc is Swiss tax resident because its executive management is in Zurich. That conclusion needs more evidence. Incorporation, effective management and tax residence are separate legal concepts.
The Alcan connection: The historical connection is interesting, but I’d want to establish precisely how much of Amcor’s Swiss industrial heritage can be traced to Alusuisse.
6. One major development missing from the article
Amcor completed its acquisition of Berry Global on April 30, 2025.
This substantially changed Amcor’s size. The combined company now has approximately 400 manufacturing facilities in more than 40 countries and around 75,000 employees. SEC+1
There is also an interesting development for Switzerland: Amcor’s 2026 annual filing says it expects to begin moving and consolidating selected corporate functions to a new US headquarters in Miami in 2027. Zurich remains its primary executive office at the time of that filing. SEC
That would make an interesting follow-up article.
My overall verdict
I like the concept of this post. It is not a conventional financial analysis, nor does it pretend to be one. It is an exploration of a large international company through a series of questions.
However, I would distinguish between:
Facts verified against corporate records.
Explanations supplied by Gemini.
Conclusions that still need independent verification.
That distinction matters particularly when discussing publicly traded companies.
And one final observation: Your original image says «HERE IT IS.» I think that works rather nicely as the introduction to this article.
You have now delivered on the announcement!
I’d be interested in seeing Baarda.ch develop a little series exploring international companies with Swiss headquarters. Amcor is a particularly good starting point.
Gemini: At its core, VAT Group AG exists because modern microelectronics and high-tech manufacturing cannot function without extreme, near-perfect vacuum environments.
While it operates quietly behind the scenes as a component supplier, VAT serves a critical, structural role in the global technology supply chain. Its primary existence boils down to three core reasons:
1. Solving the Nano-Scale Contamination Problem
In semiconductor manufacturing (especially as node sizes shrink below 3nm for AI accelerators, mobile chips, and advanced memory), a single stray dust particle or molecular impurity can ruin an entire silicon wafer.
Advanced manufacturing processes—like Extreme Ultraviolet (EUV) lithography, Atomic Layer Deposition (ALD), and plasma etching—require Ultra-High Vacuum (UHV) conditions to operate.
VAT exists to design high-precision vacuum valves, transfer gates, and isolation modules that seal and control these process chambers without generating friction particles or allowing outgassing.
2. Enabling Scale for Semiconductor Capital Equipment OEMs
Equipment giants like ASML, Applied Materials, Lam Research, and Tokyo Electron do not specialize in high-end mechanical vacuum sealing; they specialize in optics, plasma physics, and chemistry.
VAT serves as an essential co-engineering partner.
By designing custom, highly reliable valves with extreme cycle counts (opening and closing millions of times without failing), VAT enables toolmakers to focus on process performance while guaranteeing chamber isolation and pressure control.
3. Serving Critical Adjacent High-Tech Sectors
While semiconductors generate the majority of its business, VAT’s technical capability in high-vacuum isolation extends to several other specialized industries:
Photovoltaics & Displays: Manufacturing solar cells, OLEDs, and advanced flat panels.
Big Science & Particle Physics: Maintaining extreme vacuum conditions in large particle accelerators (such as CERN’s LHC) and gravitational wave detectors (LIGO).
Industrial & Medical Equipment: Precision electron-beam welding, optics coating, and mass spectrometry instruments.
Economic & Strategic Position
From a business standpoint, VAT exists to capture high-margin, high-moat economics in a niche industrial segment. Because qualifying a single valve into a semiconductor production line takes years of rigorous testing, the switching costs for OEMs are exceptionally high.
As a result, VAT commands a global market share estimated near 70% in high-performance vacuum valves, making it an indispensable choke-point company for global digitalization and AI infrastructure.
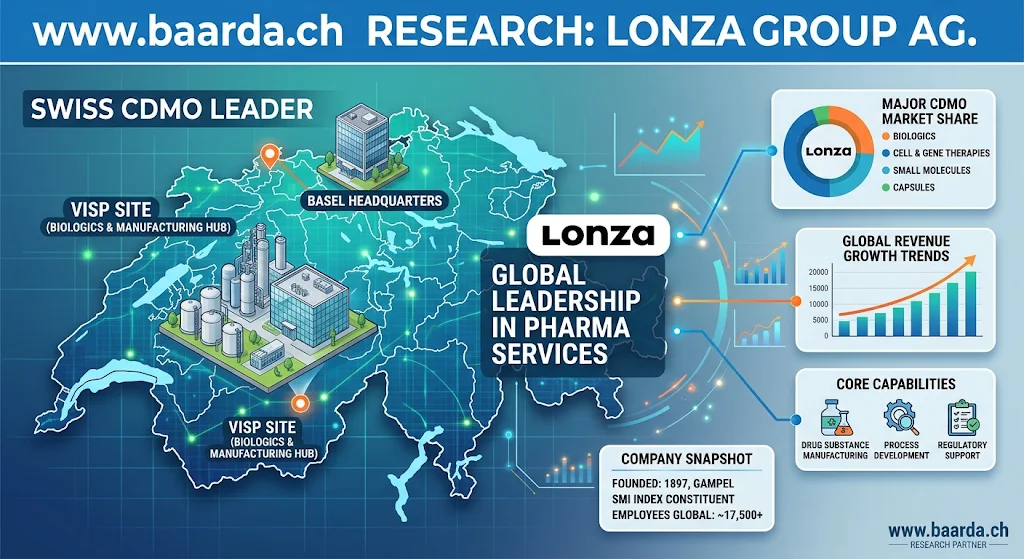
Gemini: Yes, Lonza Group AG is deeply and historically Swiss.
It was founded back in 1897 in Gampel, in the Swiss canton of Valais, originally taking its name from the Lonza river that flows out of the Lötschental. Today, its corporate headquarters are located in Basel, and it maintains massive operational and manufacturing footprints within Switzerland—most notably its sprawling production and development hub in Visp, alongside sites like Stein.
From a market and financial perspective, it is a heavyweight blue-chip component of the Swiss stock market, listed on the SIX Swiss Exchange and featuring prominently on the Swiss Market Index (SMI). While it has grown into a global contract development and manufacturing organization (CDMO) serving the worldwide pharma and biotech sectors, its identity, governance, and core infrastructure remain anchored tightly to Switzerland.
Reint Jelger: Does Lonza Group AG do good things for Switzerland, and the World?
Google Gemini: Lonza plays a massive role in both the Swiss economy and the global healthcare landscape, though like any major industrial and chemical giant, its impact is viewed through a few different lenses.
What Lonza does for Switzerland
Economic Anchor & Employment: Lonza is one of Switzerland’s premier industrial employers. Its massive site in Visp (Valais) has transformed the region into a high-tech biotechnology cluster, creating thousands of specialized engineering, scientific, and manufacturing jobs.
Tax Base & Market Weight: As a multi-billion-franc anchor of the Swiss Market Index (SMI), it contributes heavily to corporate tax revenues in its home cantons and represents a major pillar of Switzerland’s export-driven, high-value manufacturing economy.
National Prestige in Science: It helps maintain Switzerland’s reputation as a global hub for chemical and pharmaceutical innovation—carrying forward a tradition that dates back to the 19th century.
What Lonza does for the World
Scaling Life-Saving Medicines: As a Contract Development and Manufacturing Organization (CDMO), Lonza doesn’t just sell its own drugs; it builds and operates the complex infrastructure required to manufacture breakthrough treatments invented by biotech and pharma pioneers.
Global Health Infrastructure: During major public health demands—such as producing ingredients and viral vector components for global vaccine rollouts or manufacturing antibody-drug conjugates (ADCs) used in advanced cancer treatments—Lonza’s massive facilities act as a backbone for worldwide medical supply chains.
Environmental Standards: The company has faced pressure historically due to its roots in heavy chemical production, but modern corporate mandates have pushed it toward strict science-based sustainability targets, aiming for major cuts in greenhouse gas intensity and waste.
Ultimately, while it operates for profit as a multinational enterprise, its daily output directly dictates whether complex, life-saving therapies can actually be manufactured at a scale that serves patients globally.
Reint Jelger: 659,60 CHF is their current share price I see
Gemini: Spot on—Lonza (LONN) traded right around 659.60 CHF on the SIX Swiss Exchange today.
That puts its total market capitalization at approximately 46.3 billion CHF, reflecting the major rally it has had over the past year (up over 20% from its 52-week lows down around 454 CHF).
At that valuation, it trades at a forward P/E multiple around 31x to 40x earnings with a modest dividend yield (~0.75%–0.80%), as investors price in its high-margin growth from biologics and antibody-drug conjugate (ADC) drug manufacturing.
Google Gemini: Yes, Compagnie Financière Richemont SA makes far more than 1,000 Swiss Francs in profit a year. In fact, it generates billions of Euros (and Francs) annually.
In the 2026 financial year, Richemont reported:
Operating Profit:€4.5 billion (~CHF 4.3 billion)
Net Profit:€3.5 billion (~CHF 3.3 billion)
Even on a single-share level, the company pays an annual dividend of CHF 3.30 per share (plus extra special dividends), totaling over CHF 2 billion returned directly to shareholders each year.
Gemini: Compagnie Financière Richemont SA is the 100% owner of Van Cleef & Arpels.
Here is how the connection breaks down:
Ownership: Richemont initially acquired a controlling 60% stake in the French high-jewelry Maison in 1999 and bought out the remaining shares to take full 100% ownership in 2003.
Core Revenue Driver: Along with Cartier, Van Cleef & Arpels forms the core of Richemont’s Jewellery Maisons division. It generates billions of euros in revenue each year and stands as one of the conglomerate’s most profitable assets.
Leadership Tie: The relationship is so central to the group that Nicolas Bos, who spent over a decade serving as President & CEO of Van Cleef & Arpels, was appointed as the overall Chief Executive Officer (CEO) of Compagnie Financière Richemont SA.
Reint Jelger: I see the price of one share is currently: 174,70 CHF, what if someone would buy one, would they then be co-owner of Compagnie Financière Richemont SA?
Gemini: Yes, purchasing one A share of Compagnie Financière Richemont SA legally makes you a fractional co-owner (shareholder) of the company.
Holding even a single share grants specific legal ownership rights:
Proportional Equity Claim: You own approximately 1 out of the ~537.6 million outstanding A shares. You hold a micro-fraction of everything the parent company owns, including its brand portfolio (Cartier, Van Cleef & Arpels, IWC, Montblanc) and net assets.
Dividend Rights: You are entitled to receive any dividend voted on by the board.
Voting Rights & AGM Access: You have the right to register the share in your name, vote at the Annual General Meeting (AGM), or appoint a proxy to vote on your behalf.
Compagnie Financière Richemont SA reports its official financial numbers in Euros (€).
While it is a Swiss company headquartered in Bellevue (Geneva) with its primary stock listing in Swiss Francs (CHF) on the SIX Swiss Exchange, its accounting structure uses two distinct currencies:
Reporting Currency (Euros): Richemont presents its consolidated financial statements in Euros. Because a vast portion of its global sales, operations, and key European Maisons (such as Cartier, Van Cleef & Arpels, and Buccellati) are tied to the Eurozone, using the Euro provides a clearer picture of its underlying operational performance.
Dividend Currency (Swiss Francs): Dividends proposed by the Board of Directors and paid out to shareholders are declared and distributed in Swiss Francs.